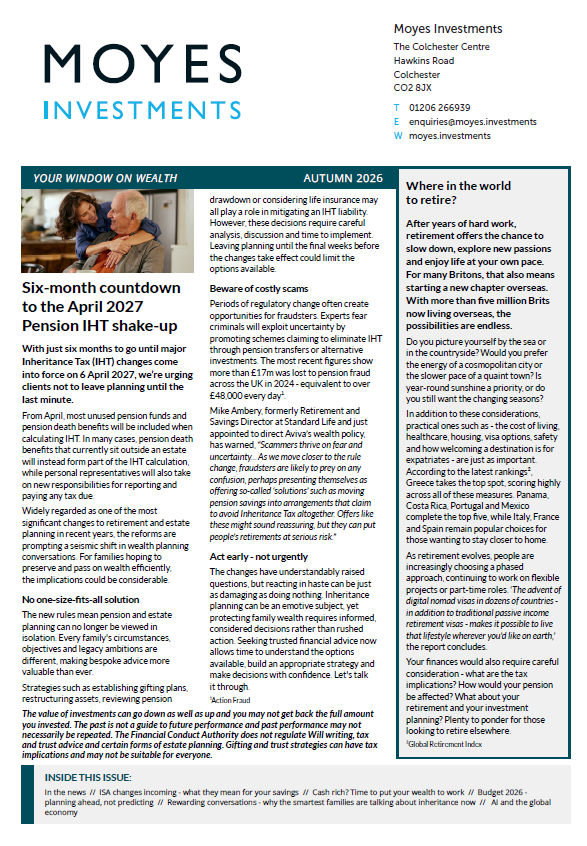
With just six months to go until major Inheritance Tax (IHT) changes come into force on 6 April 2027, we’re urging clients not to leave planning until the last minute.
From April, most unused pension funds and pension death benefits will be included when calculating IHT. In many cases, pension death benefits that currently sit outside an estate will instead form part of the IHT calculation, while personal representatives will also take on new responsibilities for reporting and paying any tax due. Widely regarded as one of the most significant changes to retirement and estate planning in recent years, the reforms are prompting a seismic shift in wealth planning conversations. For families hoping to preserve and pass on wealth efficiently, the implications could be considerable.
No one-size-fits-all solution
The new rules mean pension and estate planning can no longer be viewed in isolation. Every family’s circumstances, objectives and legacy ambitions are different, making bespoke advice more valuable than ever. Strategies such as establishing gifting plans, restructuring assets, reviewing pension drawdown or considering life insurance may all play a role in mitigating an IHT liability. However, these decisions require careful analysis, discussion and time to implement. Leaving planning until the final weeks before the changes take effect could limit the
options available.
)